

Aisha Steel Mills Limited: performance and outlook
Aisha Steel Mills Limited (ASL) experienced volatile performance from 2021-2026, marked by significant growth, sharp declines, and recent recovery driven by market dynamics and policy changes.
- ASL's volatile financial performance and market challenges (2021-2026).
- Impact of government policies, global steel prices, and currency.
- Strategic role of exports and domestic demand drivers.
- Future outlook on industry growth and cost pressures.
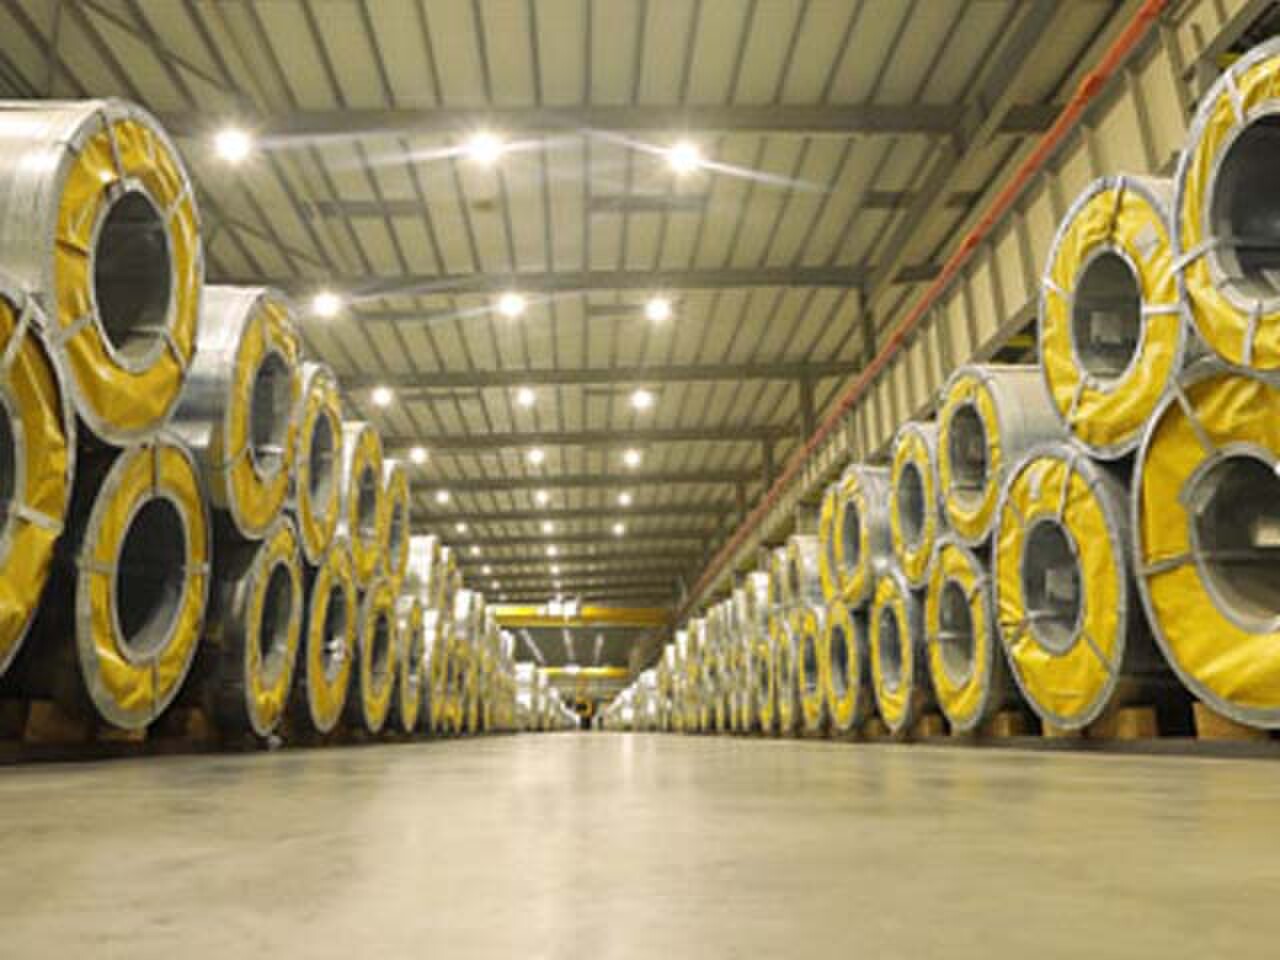
Aisha Steel Mills Limited (PSX: ASL) was incorporated in Pakistan in 2005 as a public limited company and started its commercial operations in 2012.
The company is engaged in the manufacturing and sale of cold rolled coils and hot dipped galvanized coils.
ASL is a company of Arif Habib Group and is one of the largest private sector investments in the local flat-rolled steel industry. Having its production unit strategically located at the Port Qasim, Karachi, the company not only caters to the local demand but also exports to many international destinations.
The primary export destinations of ASL include North America, Asia, Africa, Europe and Middle East. ASL’s products serve as an important raw material to automobile, engineering and appliances industry which in turn produce value-added products for the local and export markets.
Pattern of Shareholding
As of June 30, 2026, ASL has a total of 930.785 million shares outstanding which are held by 10,188 shareholders. Associated companies, undertakings and related parties have the majority stake of 53.07 percent in ASL followed by Directors, their spouse and minor children holding 20.15 percent of ASL’s shares.
Local general public accounts for 15.13 percent of the outstanding shares of ASL while Banks, DFIs and NBFIs hold 2.08 percent shares.
Around 1.44 percent of the company’s shares are held by Modarabas and Mutual funds. The remaining shares are held by other categories of shareholders.
Historical Performance (2021-26)
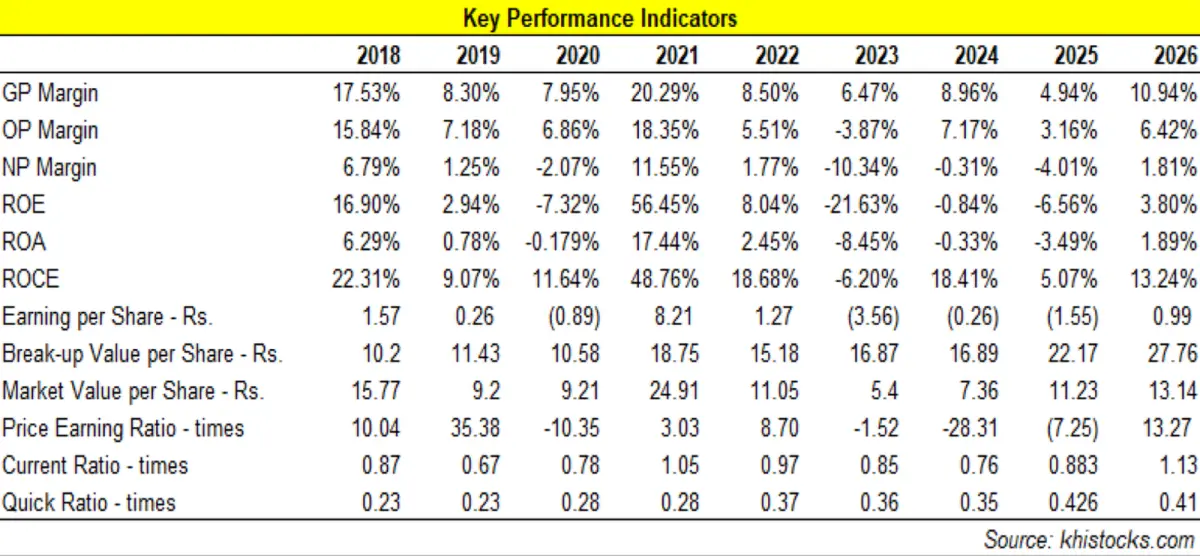
ASL’s topline which has been riding an upward trajectory since 2019 registered a massive plunge in 2023. This was followed by a rebound in 2024. The company’s bottomline and margins followed a declining trend until 2020 followed by a staggering turnaround in 2021.
The bottomline and margins got back to its downward trajectory in 2022 and 2023. ASL registered net losses in 2020, 2023 and 2024. In 2024, net loss greatly reduced while gross and operating margins slightly ticked up. The detailed performance review of the period under consideration is given below.
FY21 appears to be the most fortunate year for ASL as not only did its sales volume grew by around 47 percent year-on-year to clock in at 379,622 tons, its topline multiplied by 85.10 percent year-on-year to clock in at Rs.55,116.37 million. This was on account of reforms implemented by the government of Pakistan to deal with economic imbalance. These included Rs.1.24 trillion package in the construction industry.
This was the year when the local as well as global economy was recovering from the shocks of COVID-19 and massive trade and industrial activity took place in almost all the segments of the economy. This resulted in increase in the demand of commodities with steel being no exception. The global prices of steel peaked in 2021, however, Pak Rupee somewhat stabilized. ASL was also able to pass on the impact of cost hike to its consumers.
As a consequence, gross profit mounted by 372.72 percent in 2021 with GP margin jumping up to 20.29 percent from 7.95 percent in the previous year. In 2021, ASL not only performed brilliantly in the local market but its export sales also posted a massive rebound especially in North American and Asian. As a result of export sales, selling and distribution cost also picked up by 470.70 percent, particularly in the category of export clearance charges.
This could’ve diluted the operating profit, but a considerable growth in other income on account of exchange gain saved the day and ASL attained OP margin of 18.35 percent in 2021– the highest since 2017. This was against the OP margin of 6.86 percent posted in 2020. In absolute terms, operating profit strengthened by 394.98 percent in 2021.
Finance cost also slumped by 55 percent in 2021 due to monetary easing. All these factors led to net profit of Rs.6368.35 million in 2021 with EPS of Rs.8.21 and NP margin of 11.55 percent. This was against the net loss of Rs.616.57 million and loss per share of Rs.0.89 posted in 2020.
After bidding farewell to a blissful 2021, came a year full of challenges and shocks. Steel prices touched record high on the back of commodity super cycle in the international market. This coupled with weaker local currency proved to be a double whammy for ASL.
Local economic activity remained suppressed due to political upheaval, high inflation and enormous fiscal imbalances. This resulted in 19 percent year-on-year fall in ASL’s sales volume to clock in at 306,213 tons.
ASL’s topline grew by 17.62 percent year-on-year to clock in at Rs.64,830.42 million in 2022 primarily on account of upward revision in the prices of its products. Although international steel prices corrected in 2022, sharp depreciation in the value of Pak Rupee gave no respite to the cost of sales and GP margin plummeted to 8.51 percent, from its historic high of 20.29 percent in 2021. Gross profit also turned out to be 50.71 percent thinner than the last year level.
Export sales showed an improvement particularly in the North American market; consequently, export clearance charges grew. This pushed selling and distribution charges up by 76.31 percent year-on-year in FY22. Administrative expense also surged by 10.85 percent year-on-year in 2022. Other income massively dropped as exchange gain realized in 2021 on the back of stable currency vanished in 2022.
Operating profit slipped by 64.66 percent year-on-year in 2022 with OP margin drastically falling to 5.513 percent. Finance cost grew by 50.83 percent in 2022 owing to multiple hikes in the discount rate as well as increased working capital related borrowings. As a result, bottom line shrank by 82 percent year-on-year to clock in at Rs.1146.11 million in 2022 with EPS of Rs.1.27 and NP margin of 1.77 percent.
In 2023, ASL’s topline couldn’t keep pace with the economic and political headwinds circling the economy and dwindled by 52 percent year-on-year. Sales volume registered 60 percent year-on-year contraction to clock in at 122,334 tons in 2023. This was on account of slower demand due to sluggish business activity which was the return of import restrictions, demand suppression as well as devastating floods which destroyed the infrastructure and agricultural sector to a huge extent. Net sales tumbled by 52 percent to clock in at Rs. 31,102.38 million in 2023.
Cost of sales slid by 50.96 percent year-on-year in 2023. Although steel prices tapered off in 2023 due to slowdown of major economies, ASL was not able to retain its GP margin owing to sharp depreciation of Pak Rupee. Gross profit nosedived by 63.48 percent year-on-year in 2023 with GP margin touching its 6-year lowest level of 6.47 percent.
Distribution expense eroded by 66.36 percent year-on-year in 2023 due to decreased export sales. Administrative expense inched up by 4.51 percent year-on-year in 2023 due to high inflation. Massive exchange loss resulted in 131.83 percent spike in other expense in 2023.
ASL registered operating loss of Rs.1203.79 million in 2023. Finance cost didn’t give any breather and surged by 58.23 percent year-on-year in 2023. This coupled with increase in local taxes further worsened ASL’s net loss which stood at Rs.3215.65 million in 2023 with loss per share of Rs.3.56.
In 2024, ASL registered 37.45 percent year-on-year improvement in its net sales which clocked in at Rs.42,749.65 million. This was the result of 34.66 percent increase in the company’s sales volume coupled with 2 percent upward price revision. The improvement in demand was driven by automotive and infrastructure industries primarily on account of low-base of last year.
Decline in international steel prices due to slowdown in China coupled with the resilience exhibited by Pak Rupee resulted in 90.24 percent increase in gross profit in 2024. GP margin also ticked up to 8.96 percent in 2024. Distribution expense mounted by 301.24 percent in 2024 due to higher export sales.
Administrative expense ticked up by 8 percent in 2024 due to higher payroll expense on account of inflationary pressure.
The company squeezed its workforce from 674 employees in 2023 to 625 employees in 2024. Other expense slid by 99.79 percent in 2024 as no exchange loss was recorded during the year. Conversely, other income grew by 83.21 percent in 2024 due to exchange gain. ASL recorded a hefty operating profit of Rs.3064.22 million in 2024 with OP margin of 7.17 percent. This was against operating loss recorded in the previous year.
Finance cost ticked up by 6.14 percent in 2024 due to higher discount rate. ASL recorded net loss of Rs.132.47 million in 2024, down 95.88 percent year-on-year. This translated into loss per share of Rs.0.26 in 2024.
ASL’s topline registered 21 percent year-on-year decline in 2025 to clock in at Rs.33,751.70 million. This was due to sluggish demand from China, US and Europe and stiff competition from importers in the local market. The company sold 162,599 tons in 2025, down 9.59 percent year-on-year.
The decline in international CRC prices and cutthroat competition from importers forced the local companies including ASL to reduce its prices to foster sales. This resulted in 56.48 percent shrinkage in gross profit in 2025 with GP margin falling down to 4.94 percent. 15.48 percent contraction in distribution expense in 2025 was largely due to lesser export clearance charges incurred during the year.
Administrative expense multiplied by 30.49 percent in 2025 owing to inflationary pressure which drove up the payroll expense. Number of employees also increased from 625 in 2024 to 630 in 2025.
Massive hike of 1164.22 percent in other expense in 2025 was the result of exchange loss and loss on disposal of fixed assets. Other income multiplied by 111 percent in 2025 due to gain worth Rs.550 million recognized on insurance claim related to the fire incident at the Cold Rolling & Skin-Pass Mill (CRSM) plant. Operating profit weakened by 65.21 percent in 2025 with OP margin falling down to 3.16 percent.
Finance cost tapered off by 29.23 percent in 2025 due to monetary easing. This was despite higher outstanding borrowings at the end of the year. The company posted net loss of Rs.1351.85 million in 2025, up 920.50 percent year-on-year. This translated into loss per share of Rs.1.55 in 2025.
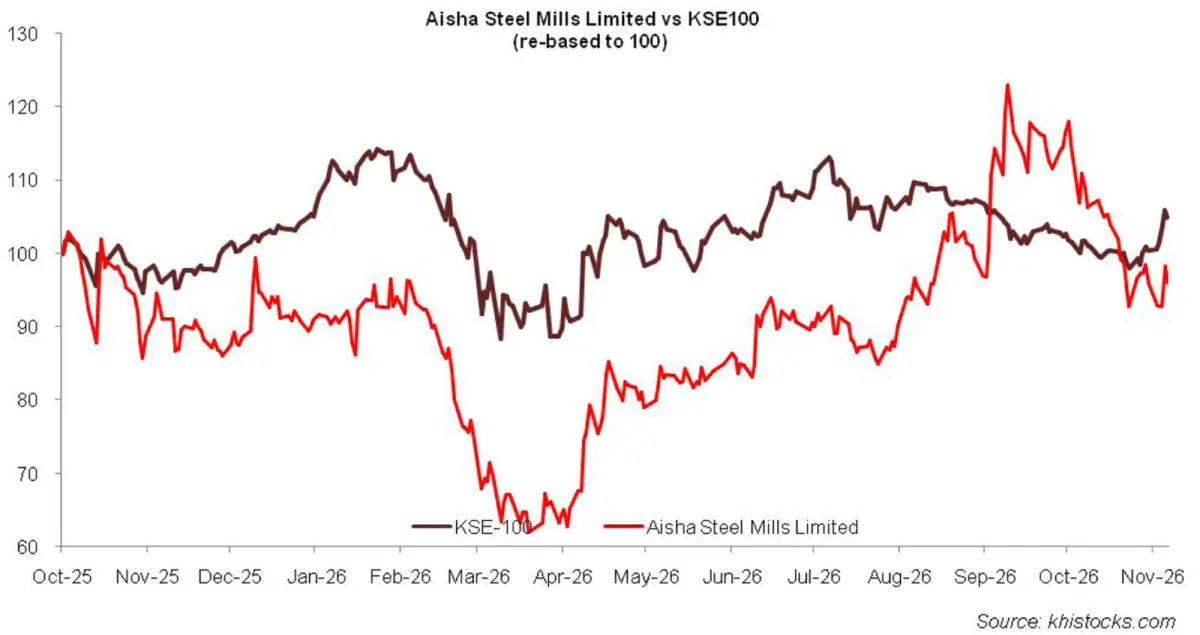
In 2026, ASL’s net sales staggeringly grew by 60.69 percent to clock in at Rs.54.235.22 million. This was due to recovery in the steel demand in the local market. Importers from FATA/PATA region who were previously exempted from tax are now subject to 12 percent sales tax which provided a level playing field to the local players.
ASL’s sales volume clocked in at 257,144 tons in 2026, up 72.65 percent year-on-year. This also included export sales volume of 61,583 tons in 2026, up 141.92 percent year-on-year. While the imposition of 50 percent tax by the US government on steel imports from various countries resulted in lower exports of ASL to the US region, however, stronger sales to Europe buttressed the export volumes in 2026.
Improved sales volume, stable international HRC prices and steady local currency enabled the company to record 255.83 percent stronger gross profit in 2026 with GP margin climbing up to 10.94 percent.
Distribution expense mounted by 243.89 percent in 2026 on the back of higher export freight charges which was the consequence of increased export volume as well as elevated international freight charges due to geopolitical tensions.
Administrative expense ticked up by 9 percent in 2026 due to higher payroll expense as workforce was expanded to 691 employees. 191.95 percent escalation in other expense in 2026 was the result of provisioning done for WWF and WPPF as well as exchange loss. Other income deteriorated by 88.82 percent in 2026 due to high-base effect as the company recognized gain on insurance claim in the previous year.
Operating profit strengthened by 226.68 percent in 2026 with OP margin picking up to 6.42 percent. Finance cost dipped by 36.79 percent in 2026 due to decline in average borrowing rates and a sponsor net injection of Rs. 3,919 million which helped reduce the borrowing levels. ASL registered net profit of Rs.981.149 million in 2026. This translated into EPS of Rs.0.99 and NP margin of 1.81 percent in 2026.
Recent Performance (1QFY27)
During the first quarter of the ongoing fiscal year, ASL recorded a massive 90.64 percent year-on-year growth in its net sales which clocked in at Rs.18,039.27 million. This came on the back of a robust 85 percent growth in the sales volume of the company which clocked in at 80,053 tons in 1QFY27.
The sale volume also included export dispatches of 8634 tons in 1QFY27, up 47.44 percent year-on-year. Improvement in the performance of domestic automotive and white goods industries buttressed ASL’s local sales during the period. The imposition of 12 percent sales tax on the importers also enabled the local steel industry to grab a greater share of the market.
Export sales strengthened on the back of a spike in the steel prices in the US market which made imported steel lucrative to the US customers even after the imposition of 50 percent tariff on imports.
Increased sales volume and range bound international HRC prices enabled ASL to record 110 percent stronger gross profit in 1QFY27 with GP margin clocking in at 10.74 percent versus 9.74 percent in 1QFY26.
Distribution expense surged by 168.95 percent in 1QFY27 mainly on the back of greater freight charges on export sales. Administrative expense multiplied by 35.29 percent in 1QFY27 due to inflationary pressure and the enhancement of the company’s operations.
Profit related provisioning and exchange loss pushed up other expense by 806.87 percent in 1QFY27. Conversely, other income deteriorated by 3.68 percent in 1QFY27 due to thinner scrap sales.
ASL registered 85.76 percent stronger operating profit in 1QFY27, however, OP margin slightly dipped to 5.62 percent versus 5.76 percent in 1QFY26. Finance cost dipped by 7.69 percent in 1QFY27 due to lesser average borrowing rates on the outstanding borrowings.
ASL posted net profit of Rs.335.96 million in 1QFY27, up 309.51 percent year-on-year. This translated into EPS of Rs.0.34 and NP margin of 1.86 percent in 1QFY27 versus EPS of Rs.0.07 and NP margin of 0.87 percent registered in 1QFY26.
Future Outlook
Modest growth seen in the automobile and white goods sectors may prove to be a good omen from the steel manufacturers in 2027. Policy changes by FBR in the Finance bill are discouraging greater exports from FATA/PATA region. This will result in gradual demand recovery for the formal sector.
Volatility in the international HRC prices, energy cost and freight rates may put pressure on margins and profitability.



















Comments